Sunday 27 / September / 2026
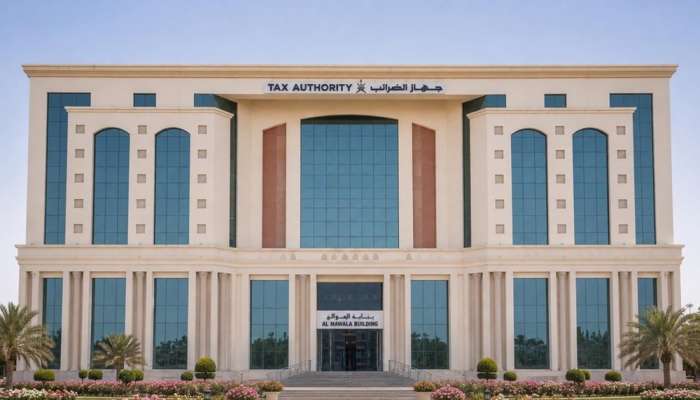
Muscat: The Tax Authority issued today three new administrative decisions designating the goods and products subject to value-added tax at a zero percent rate to include basic food commodities, human medicines and medical equipment, as well as veterinary medicines and medical equipment, all of which shall enter into force as of 1 October 2026.
These decisions come within the framework of the Sultanate of Oman's keenness to strengthen the social protection system, alleviate living and financial costs and burdens on citizens and residents, and support vital sectors such as health, agriculture, and animal wealth.
In detail, the first decision provides for subjecting a broad and comprehensive list of basic food commodities and materials to the zero percent rate. The exemptions include livestock and live animals of cattle, sheep, goats, camels, and poultry designated for breeding, slaughter, or milk production, as well as various types of beef, sheep, goat, camel, and poultry meat in all their fresh, chilled, frozen, and minced forms.
The decision also covers a wide range of fish and seafood, whether live, fresh, or frozen, in addition to basic dairy products including long-life and evaporated milk, yoghurt, labneh, butter, and cheeses of various types, as well as table and hatching eggs, fresh and dried vegetables and fruits, legumes, coffee and tea, and various spices and seasonings. Under this decision, the previous Decision No. (65/2021) and all provisions conflicting with its new provisions shall be repealed.
The second decision comes as a continuation of national efforts aimed at supporting the health sector and providing medical and pharmaceutical supplies and products at appropriate prices for patients and consumers.
The decision provides for subjecting supplies of medicines, herbal medicines, biological and health preparations, foods for medical uses, and medical equipment to value-added tax at a zero percent rate, provided that a release permit is issued therefor by the Ministry of Health in accordance with the approved customs heading. The products covered in the annex include antibiotics, hormones, vaccines, blood serums, infant foods, foods designated for medical conditions, medical solutions, oxygen gas, dental products, as well as smoking cessation products such as patches and sprays. This decision replaces the previous Decision No. (59/2021) in order to unify the regulatory frameworks.
In the same context, the third decision came in support of the agricultural and animal sector and to alleviate costs on breeders and companies operating in this field. The decision provides for subjecting supplies of veterinary medicines and medical equipment specified in the annex to the decision to value-added tax at a zero percent rate, whenever a release permit is issued therefore by the Ministry of Agriculture, Fisheries and Water Resources in accordance with their customs codes.
The covered list is diverse, encompassing veterinary vaccines and serums, biological toxins, antibiotics such as penicillin and streptomycin, vitamins, minerals, and nutritional supplements, in addition to solutions, gel preparations, and experimental instruments used in veterinary examinations and procedures.
The Tax Authority affirmed that the goods and products covered by the three decisions are specified in the annexes attached thereto in accordance with the unified customs tariff codes, thereby contributing to clarity regarding the scope of goods subject to the zero percent rate and facilitating the implementation of the decisions. These decisions shall enter into force as of 1 October 2026.